
The diversification of textile supply chains away from China is already underway, accelerated by the numerous changes to US trade policy since 2025. Whilst these US textile tariffs now appear to have stabilised, the balance of power amongst clothing-producing countries is undergoing significant upheaval. In 2025, Coface published a study ranking the most competitive countries for textile production outside China. This ranking has now been updated to reflect the most recent US tariffs.
Changes to the US tariff framework are altering the ranking of the most competitive countries in the clothing and footwear sectors.
They could strengthen the position of several Asian and African suppliers, whilst confirming that diversification away from China remains a long-term structural trend,
states Eve Barre, sector economist at Coface.
China’s leadership facing increasing competition
China remains the world’s leading exporter of clothing and footwear, but its share of global exports continues to decline. This trend is driven by rising labour costs and companies’ desire to diversify their supply chains.
To identify the countries best positioned in this new landscape, Coface has updated its competitiveness index for the clothing and footwear sector, based on four pillars:
- Business environment
- access to a competitive workforce,
- social and environmental criteria,
- strength of the textile industrial ecosystem
A component relating to US tariffs has also been included. Recent changes to the US tariff framework have, in fact, altered the relative competitiveness of many producers. Despite the removal of certain tariffs, Chinese exports remain subject to higher duties than those of several competing countries. In the long term, this development could reshuffle the deck amongst the world’s major production centres.
Lesotho and Madagascar among the potential major winners
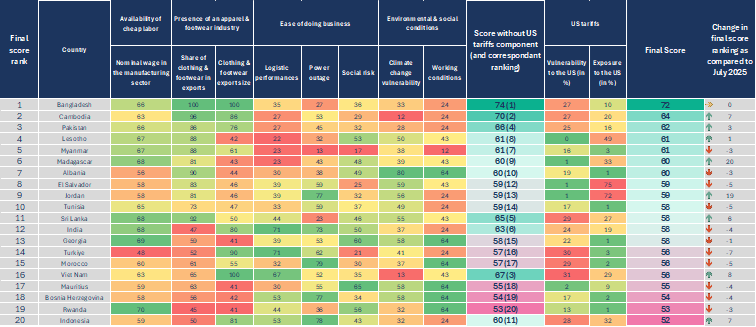
Bangladesh retains the top spot in the ranking. The main development concerns the improved competitiveness of Lesotho and Madagascar, which now feature among the top-ranked countries, having been absent from the previous edition of the ranking in the summer of 2025.
This rise is largely due to the removal of additional duties that had severely hampered their access to the US market. Other Asian countries are also strengthening their positions, including Cambodia, Pakistan and Sri Lanka, whilst Vietnam and Indonesia have entered the Top 20.
A new geography of textile sourcing
The changes in the ranking illustrate a broader reality: global competition in the textile sector is no longer driven solely by labour costs. Market access, trade policy, the depth of the industrial ecosystem and the stability of the economic framework now carry equal weight in sourcing decisions.
Against a backdrop of mounting trade tensions and the search for more resilient supply chains, companies are increasingly favouring countries capable of offering a balance between competitiveness, industrial capacity and access to major consumer markets. Recent changes to US customs tariffs depict just how quickly a shift in the trade framework can redistribute competitive advantages amongst producing countries.
Competitiveness score for the apparel and footwear industry (z-score)
Data used for the graph in .xlsx format
> What has changed in just over a year? Revisit our 2025 analysis to see how shifts in US trade policy have reshaped the relative competitiveness of apparel-producing countries.
> Explore our updated textiles and clothing sector risk assessment.


